Loading...
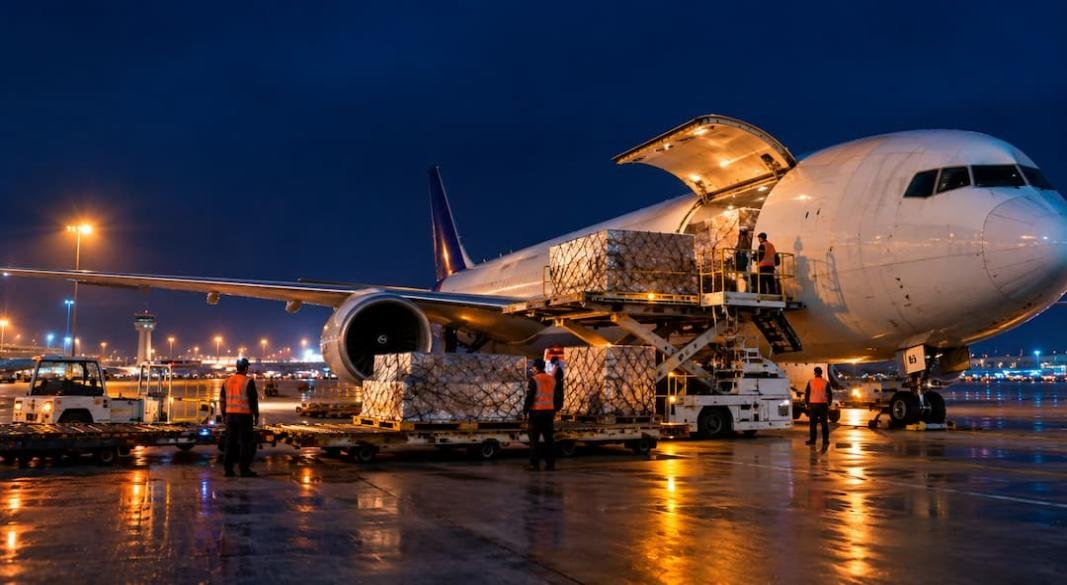
Global air cargo volumes rebounded in the week of 12–18 October, 2026 as Asian exports recovered following the Golden Week holiday period, with chargeable weight rising 2% week on week and global air freight rates increasing by 4%, according to the latest figures from WorldACD Market Data.
The recovery was led by a 9% increase in chargeable weight from Asia Pacific, offsetting declines across North America, Central and South America, the Middle East and South Asia (MESA), Europe and Africa. Global available capacity also rose by 2%, rGlobal Air Cargo Volumes Rise 2% as Asian Exports Rebound; Rates Climb 4%, reversing two consecutive weeks of 1% declines as airlines expanded freighter operations.
North America recorded a 5% week-on-week decline in chargeable weight, partly reflecting public holidays in Canada and the US. Central and South America fell by 4%, while MESA declined by 3%. Europe and Africa registered smaller contractions of 2% and 1%, respectively.
The resumption of factory and export activity following Golden Week and mid-autumn festival holidays propelled Asia Pacific volumes higher, particularly on routes to the US and Europe.
Chargeable weight from Asia Pacific to Europe rose 13% week on week, while shipments to the US increased 10%. On the transpacific trade lane, volumes from Hong Kong and mainland China to the US surged 27% and 18%, respectively. Shipments to the US increased across all Asian origins except Japan, where volumes stabilised following the post-Silver Week recovery.
South Korea led growth on Asia–Europe routes, with volumes rising 34%, followed by China at 22%, Singapore at 16% and Hong Kong at 11%. However, European-bound shipments from Vietnam, Japan and Malaysia declined.
Year on year, Asia Pacific chargeable weight to the US was up 14%, reflecting continued demand for artificial intelligence-related shipments and other technology cargo. The picture was weaker on routes to Europe, where volumes fell 16% compared with the corresponding period in 2025.
Hong Kong recorded a 32% annual decline in shipments to Europe, which WorldACD partly attributed to European Union measures aimed at curbing e-commerce parcel imports. Volumes from China and Vietnam declined 12% and 10%, respectively, while South Korea was the only Asian origin to post double-digit annual growth, increasing 14%.
Air cargo volumes from the Middle East and South Asia weakened during the week, with shipments to Europe falling 6% and those to the US declining 4%. Sharp reductions from Dubai and Sri Lanka contributed to the slowdown in US-bound traffic, while shipments from India decreased 2%.
On routes to Europe, volumes from Sri Lanka fell 15% and those from India declined 7%. Dubai bucked the trend, recording a 5% increase.
Annual comparisons, however, showed stronger performance on the US-bound trade lane. MESA chargeable weight to the US rose 24% year on year, supported by increases of 34% from India and 44% from Bangladesh. In contrast, volumes to Europe fell 13%, with Sri Lanka the only origin to avoid a decline.
Global air cargo capacity increased 2% week on week after declining in each of the previous two weeks. Asia Pacific led the expansion with a 6% rise, while capacity from Europe increased 2% and from North America and Central and South America rose 1% each. Africa and MESA recorded 2% reductions.
Across the two-week period covering weeks 41 and 42, capacity remained 1% below the preceding fortnight but was 2% higher than in the corresponding period of 2025.
Air cargo rates strengthened across all origin regions except Africa, where prices declined 4%. Rates rose 4% from Asia Pacific, 3% from Central and South America, 2% from MESA, and 1% each from Europe and North America.
The two-week comparison showed global rates up 1%, while the year-on-year picture was markedly stronger: worldwide air cargo rates were almost 30% higher than a year earlier. MESA recorded the steepest increase at 61%, followed by gains ranging from 25% to 29% across Europe, Asia Pacific, North America and Africa. Central and South America registered a more moderate 7% rise.
Rates from Asia Pacific to the US increased 6% week on week, while those to Europe rose 1%. Singapore recorded a particularly sharp 23% increase in rates to the US, with most other Asian origins posting single-digit gains. Indonesia remained unchanged.
On Asia–Europe routes, most origins recorded single-digit increases, while Thailand was unchanged. Rates from Vietnam slipped 1% and from Japan fell 8%.
Compared with the same period in 2025, Asia Pacific rates to the US were 41% higher, with increases of 34% to 48% across most routes. Rates to Europe rose 25% on average, ranging from a 16% increase for Hong Kong to 56% for Indonesia.
WorldACD noted that robust artificial intelligence-related cargo flows had strengthened expectations for a strong peak season on transpacific routes. The outlook for Asia–Europe traffic was less certain, however, as changes to EU import rules threatened to add pressure to e-commerce shipments.
From 1 November, a €2 handling fee is due to apply to non-EU e-commerce imports, in addition to the €3 customs duty per item introduced on 1 July 2026 for low-value consignments worth up to €150.
As the industry enters the final months of the year, the latest data point to a market shaped by recovering Asian export activity, firmer freight rates and expanding capacity, alongside diverging demand across major trade lanes and continued uncertainty over e-commerce flows into Europe.
IATA data shows international air cargo demand growing 8.6% year-on-year, while jet fuel prices climb 103.4%, putting pressure on airline profitability despite stronger global trade. Global air cargo demand increased by 7.7% year-on-year in September 2026, supported by stronger international trade and manufacturing activity, according to the latest figures released by the International Air Transport Association (IATA). International air cargo demand recorded even stronger growth of 8.6% compared with September 2025. However, the industry continued to face significant cost pressures, with jet fuel prices more than doubling over the year. Global cargo capacity, measured in available cargo tonne-kilometres (ACTK), expanded by 2.7% during September, while international capacity increased by 3.3%. Demand therefore continued to outpace available capacity, lifting the global cargo load factor by 2.2 percentage points to 47.9%. Fuel prices put pressure on airline profitability Marie Owens Thomsen, IATA's Senior Vice President Sustainability and Chief Economist, said air cargo demand had grown across all regions, supported by stronger global trade and manufacturing. She also highlighted the contribution of artificial intelligence-related shipments, which helped drive another month of double-digit growth across the Pacific. However, rising fuel prices remain a major challenge for the industry. Jet fuel prices increased by 17.5% month-on-month in September and were 103.4% higher than a year earlier. IATA noted that cargo yields have not kept pace with the increase in fuel prices. Its September market analysis showed cargo yields rising by 25.9% year-on-year, compared with the 103.4% increase in jet fuel prices. The disparity highlights the growing difficulty airlines face in maintaining profitability despite stronger cargo volumes. Global trade and manufacturing support demand Several economic indicators provided a supportive backdrop for air freight activity. Global trade increased by 3.6% year-on-year in August, marking the 42nd consecutive month of annual expansion. Manufacturing activity also improved. The Global Manufacturing Output Purchasing Managers' Index (PMI) increased by 0.7 points to 53.8, while the New Export Orders Index rose by 0.5 points to 51.9. Both indicators reached their highest levels in five years, signalling improved manufacturing conditions and continued support for international cargo demand. North America leads regional growth Air cargo demand increased across all six major airline regions in September, although the pace of expansion varied. North American carriers recorded the strongest growth, with demand increasing by 11.8% year-on-year, while capacity expanded by just 0.8%. Asia-Pacific airlines reported 8.6% demand growth and a 4.9% increase in capacity, reflecting continued strength in regional and trans-Pacific cargo movements. Latin American and Caribbean carriers recorded demand growth of 6.7%, alongside a 7.6% capacity expansion. African airlines saw demand rise by 4.7%, while capacity contracted by 1.2%. European carriers recorded a 4.5% increase in demand despite a 1.6% decline in capacity. Middle Eastern airlines reported the slowest regional demand growth, at 3.8%, while capacity increased by 7%. Asia–North America remains the strongest trade lane Performance across major international trade lanes remained mixed in September. The Asia–North America corridor recorded the strongest growth, with cargo traffic increasing by 17% year-on-year. This marked eight consecutive months of expansion on the route. Traffic within Asia grew by 10.2%, while Europe–North America increased by 9.3%. Europe–Asia recorded growth of 6%, extending its expansion streak to 43 consecutive months. Africa–Asia traffic increased by 2.6%. In contrast, Middle East-connected trade lanes remained under pressure. Cargo traffic between Europe and the Middle East declined by 18%, while the Middle East–Asia corridor contracted by 10.2%. Both routes recorded seven consecutive months of decline. Demand growth faces a cost challenge The September figures underline the resilience of the global air cargo market, with demand expanding faster than capacity and manufacturing indicators remaining supportive. However, higher fuel prices and the gap between operating costs and cargo yields are creating challenges for airlines seeking to convert stronger volumes into improved financial performance. For carriers, forwarders and cargo owners, the balance between demand, available capacity and fuel expenditure will remain central to market conditions in the coming months. The latest IATA data points to a growing air cargo market, but sustaining profitable growth will depend on how effectively the industry manages rising operating costs. Follow CARGOCONNECT for more such updates
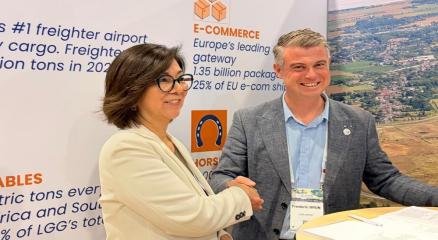
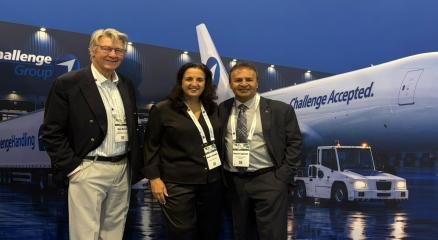
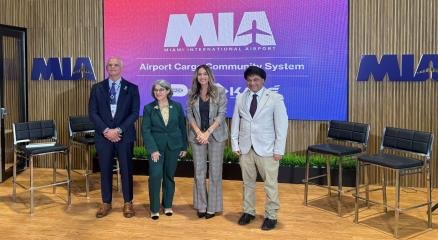
Chicago Rockford International Airport (RFD) is set to strengthen its international cargo network with the launch of a twice-weekly Boeing 777 freighter service by Challenge Group from 04 November 2026. The new route will originate at Navi Mumbai International Airport (NMI), connect through Liège Airport (LGG) in Belgium, and arrive at RFD in the United States. The service will also offer outbound connections from Rockford via Liège, leveraging Challenge Group’s network of approximately 1,500 truck movements per month to provide onward access across Europe, alongside connections to Navi Mumbai. The operation is expected to primarily handle pharmaceuticals, oversized and out-of-gauge cargo, with live animal (AVI) transportation being considered for a future phase. “Chicago is a strategically important market, serving a broad range of industries that depend on reliable international cargo connectivity,” said Or Zak, Group Chief Commercial Officer, Challenge Group. He added that the Rockford service would create additional opportunities for customers moving specialised cargo between India, Europe and the United States. For RFD, the launch supports its efforts to attract international freighter operators and develop the airport as a gateway for specialised cargo entering the US market, particularly temperature-sensitive shipments. “This new service is a direct result of our continued efforts to attract international freighter operators to Rockford, particularly the work we have undertaken to establish the airport as a leading cold chain corridor into the United States,” said Zack Oakley, Executive Director, RFD. He said the airport sees potential to expand the partnership beyond the initial twice-weekly operation through higher frequencies and support for AVI shipments. RFD is located approximately 40 miles from animal quarantine facilities, a distance comparable to that of Chicago O’Hare International Airport (ORD). The airport is also in the process of securing approval from the United States Department of Agriculture (USDA) to handle AVI shipments. According to Rene Espinet, Vice President – Cargo Business Development, RFD, the airport’s cargo-focused infrastructure and capacity to accommodate specialised freight offer operators access to the wider Chicago market, with the added benefits of operational flexibility and reduced congestion at a dedicated freighter airport. To support pharmaceutical cargo arriving on the new service, RFD will coordinate dedicated temperature-controlled trucking capacity for onward transportation to destinations in the Rockford area and warehousing facilities in Chicago. This arrangement is intended to extend cold-chain support beyond the airport and facilitate the movement of temperature-sensitive freight. Zak said Challenge Group requires airport partners that can accommodate its expanding operations and develop alongside its long-term requirements, adding that Rockford offers the capacity and flexibility to support the carrier’s growth. The announcement was made during the International Air Cargo Association (TIACA) Air Cargo Forum in Miami, held from 26 to 29 October 2026.
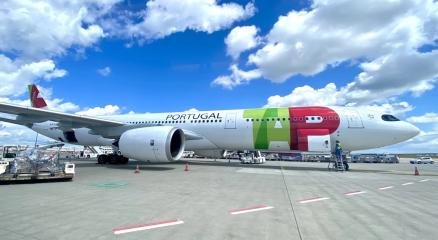
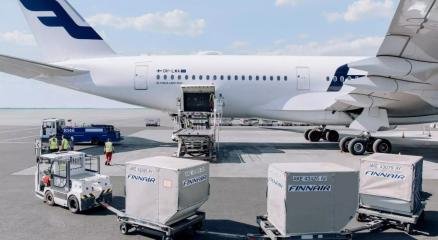
Finnair Cargo has launched its first Australian service on 25 October 2026, introducing a daily, year-round connection between Helsinki and Melbourne via Bangkok. The new route expands the airline’s international cargo network, creating additional opportunities for freight movements between Europe, Australia and North America. However, the airline has imposed initial restrictions on temperature-sensitive shipments travelling across the complete route. Daily Connectivity Via Bangkok The new service operates using an Airbus A350 passenger aircraft, with cargo carried in the aircraft’s belly hold. Flight AY145 departs Helsinki shortly after midnight and reaches Melbourne the following morning, with a technical stop in Bangkok. The return service, AY146, departs Melbourne in the afternoon and travels via Bangkok before arriving in Helsinki the next morning. The aircraft offers approximately 23 tonnes of belly-hold cargo capacity, equivalent to around 95 cubic metres, although the actual capacity available on individual flights depends on operational requirements. The schedule is designed to facilitate connections with Finnair’s wider European network through Helsinki, including onward air and road freight services. Anna-Maria Kirchner, Head of Global Sales at Finnair Cargo, said the airline had received strong interest in the new connection. She highlighted its potential to strengthen trade between Australia and Europe while supporting businesses dependent on reliable, time-sensitive logistics. Temperature-Sensitive Cargo Restrictions At launch, Finnair Cargo will not accept pharmaceuticals, perishables and other temperature-sensitive shipments as through cargo between Helsinki and Melbourne in either direction. Such consignments may be accepted separately on the Helsinki–Bangkok and Bangkok–Melbourne sectors, subject to applicable handling requirements and acceptance conditions. The restrictions are part of the airline’s initial operational approach while it conducts temperature mapping across the new route. The assessment is intended to establish the temperature conditions experienced throughout the journey, including during the Bangkok stopover. Finnair Cargo will review the restrictions after completing the exercise. The limitations are particularly relevant to pharmaceutical logistics, temperature-controlled supply chains and Australian seasonal exports, including cherries, which the airline has identified as potential cargo opportunities. Broader Cargo Market Opportunities Beyond temperature-sensitive shipments, the service is expected to support a range of commodities, including general cargo, high-tech products, industrial components, automotive parts, fashion and design goods. Seafood and other perishables may also be considered, subject to the airline’s applicable acceptance conditions and handling requirements. The Melbourne route forms part of Finnair Cargo’s winter 2026–27 network expansion, connecting the Australian market with the carrier’s Helsinki hub and its established European destinations. The addition also provides freight forwarders and logistics providers with another routing option for shipments moving between the two regions. As the service develops, the outcome of the temperature-mapping exercise will be important in determining whether the airline can expand its acceptance of sensitive cargo across the entire journey. For now, the daily connection establishes a new air freight link between Europe and Australia, with cargo capacity and commodity acceptance governed by operational requirements and the restrictions in place at launch. 𝐒𝐭𝐚𝐲 𝐓𝐮𝐧𝐞𝐝 𝐭𝐨 CARGOCONNECT 𝐟𝐨𝐫 𝐥𝐚𝐭𝐞𝐬𝐭 𝐮𝐩𝐝𝐚𝐭𝐞𝐬!